Housing and food absorbed nearly half of U.S. household spending in 2025, even as average pretax income rose faster than inflation and expenses.
Rising household income didn’t keep essential costs from taking a larger share of family budgets in 2025. Housing and food together accounted for nearly half of U.S. household spending, the highest proportion in 15 years, according to Bureau of Labor Statistics data. For owners and managers, the figures point to a consumer market where income is growing, but less of each household’s spending may be available for other purchases.
Average families spent $1,988 more on housing and food combined than they had in 2024. Housing includes rent, utilities and household furniture. Those two categories were the only major spending groups to record statistically significant increases last year, the agency’s annual Consumer Expenditure Survey found.

Income rose, while essentials claimed more
Average pretax household income reached $110,847 in 2025, up 6.4% from the prior year. That increase outpaced both inflation and the rise in total expenditures. The income gain offers an important part of the picture: households, on average, had more money coming in. Yet spending on necessities grew enough to absorb a bigger portion of what they spent.

That combination helps explain why stronger income figures can coexist with a strained sense of affordability. A household’s total income doesn’t show how much remains after recurring bills are paid. When rent, homeownership costs, utilities and groceries take more room in the budget, households may have less flexibility for discretionary purchases, even if earnings are higher.

The data describe average spending across households, so individual experiences will vary. Still, the direction matters to businesses that depend on consumer demand. When essential categories account for a larger share of spending, firms selling optional goods and services may face customers who are more selective about timing, price and quantity. The survey itself doesn’t measure those purchasing choices, but it shows why headline income growth alone may not capture customers’ available spending capacity.

Housing costs remain the biggest budget item
Housing represented 33.9% of total household expenditures in 2025, the largest share of any category. Apart from a spike in 2020 after COVID-19 hit, that was the highest housing share since 2010. The measure includes more than rent: utilities and household furniture are part of the category too, capturing several costs tied to keeping a home.
That breadth matters when interpreting the figure. Households can face higher costs through rent, homeownership expenses, utility bills or purchases for the home, and the survey groups these expenses together. The reported share doesn’t identify which one drove a particular household’s increase. It does show that, in aggregate, housing continued to dominate budgets.
For businesses, the practical read is to watch how customers respond to recurring expenses in their own markets. A household facing higher housing bills may weigh purchases differently from one whose largest costs are stable. Local customer feedback and sales patterns can help a business understand that pressure; the national average provides context, not a forecast for any one company.
Food’s share and grocery costs have climbed
Food made up 13% of household spending, the highest share since 2011. Its share has risen each year since 2020. Average food spending increased 4.6% in 2025 to $10,633, a faster pace than the increase in total expenditures.
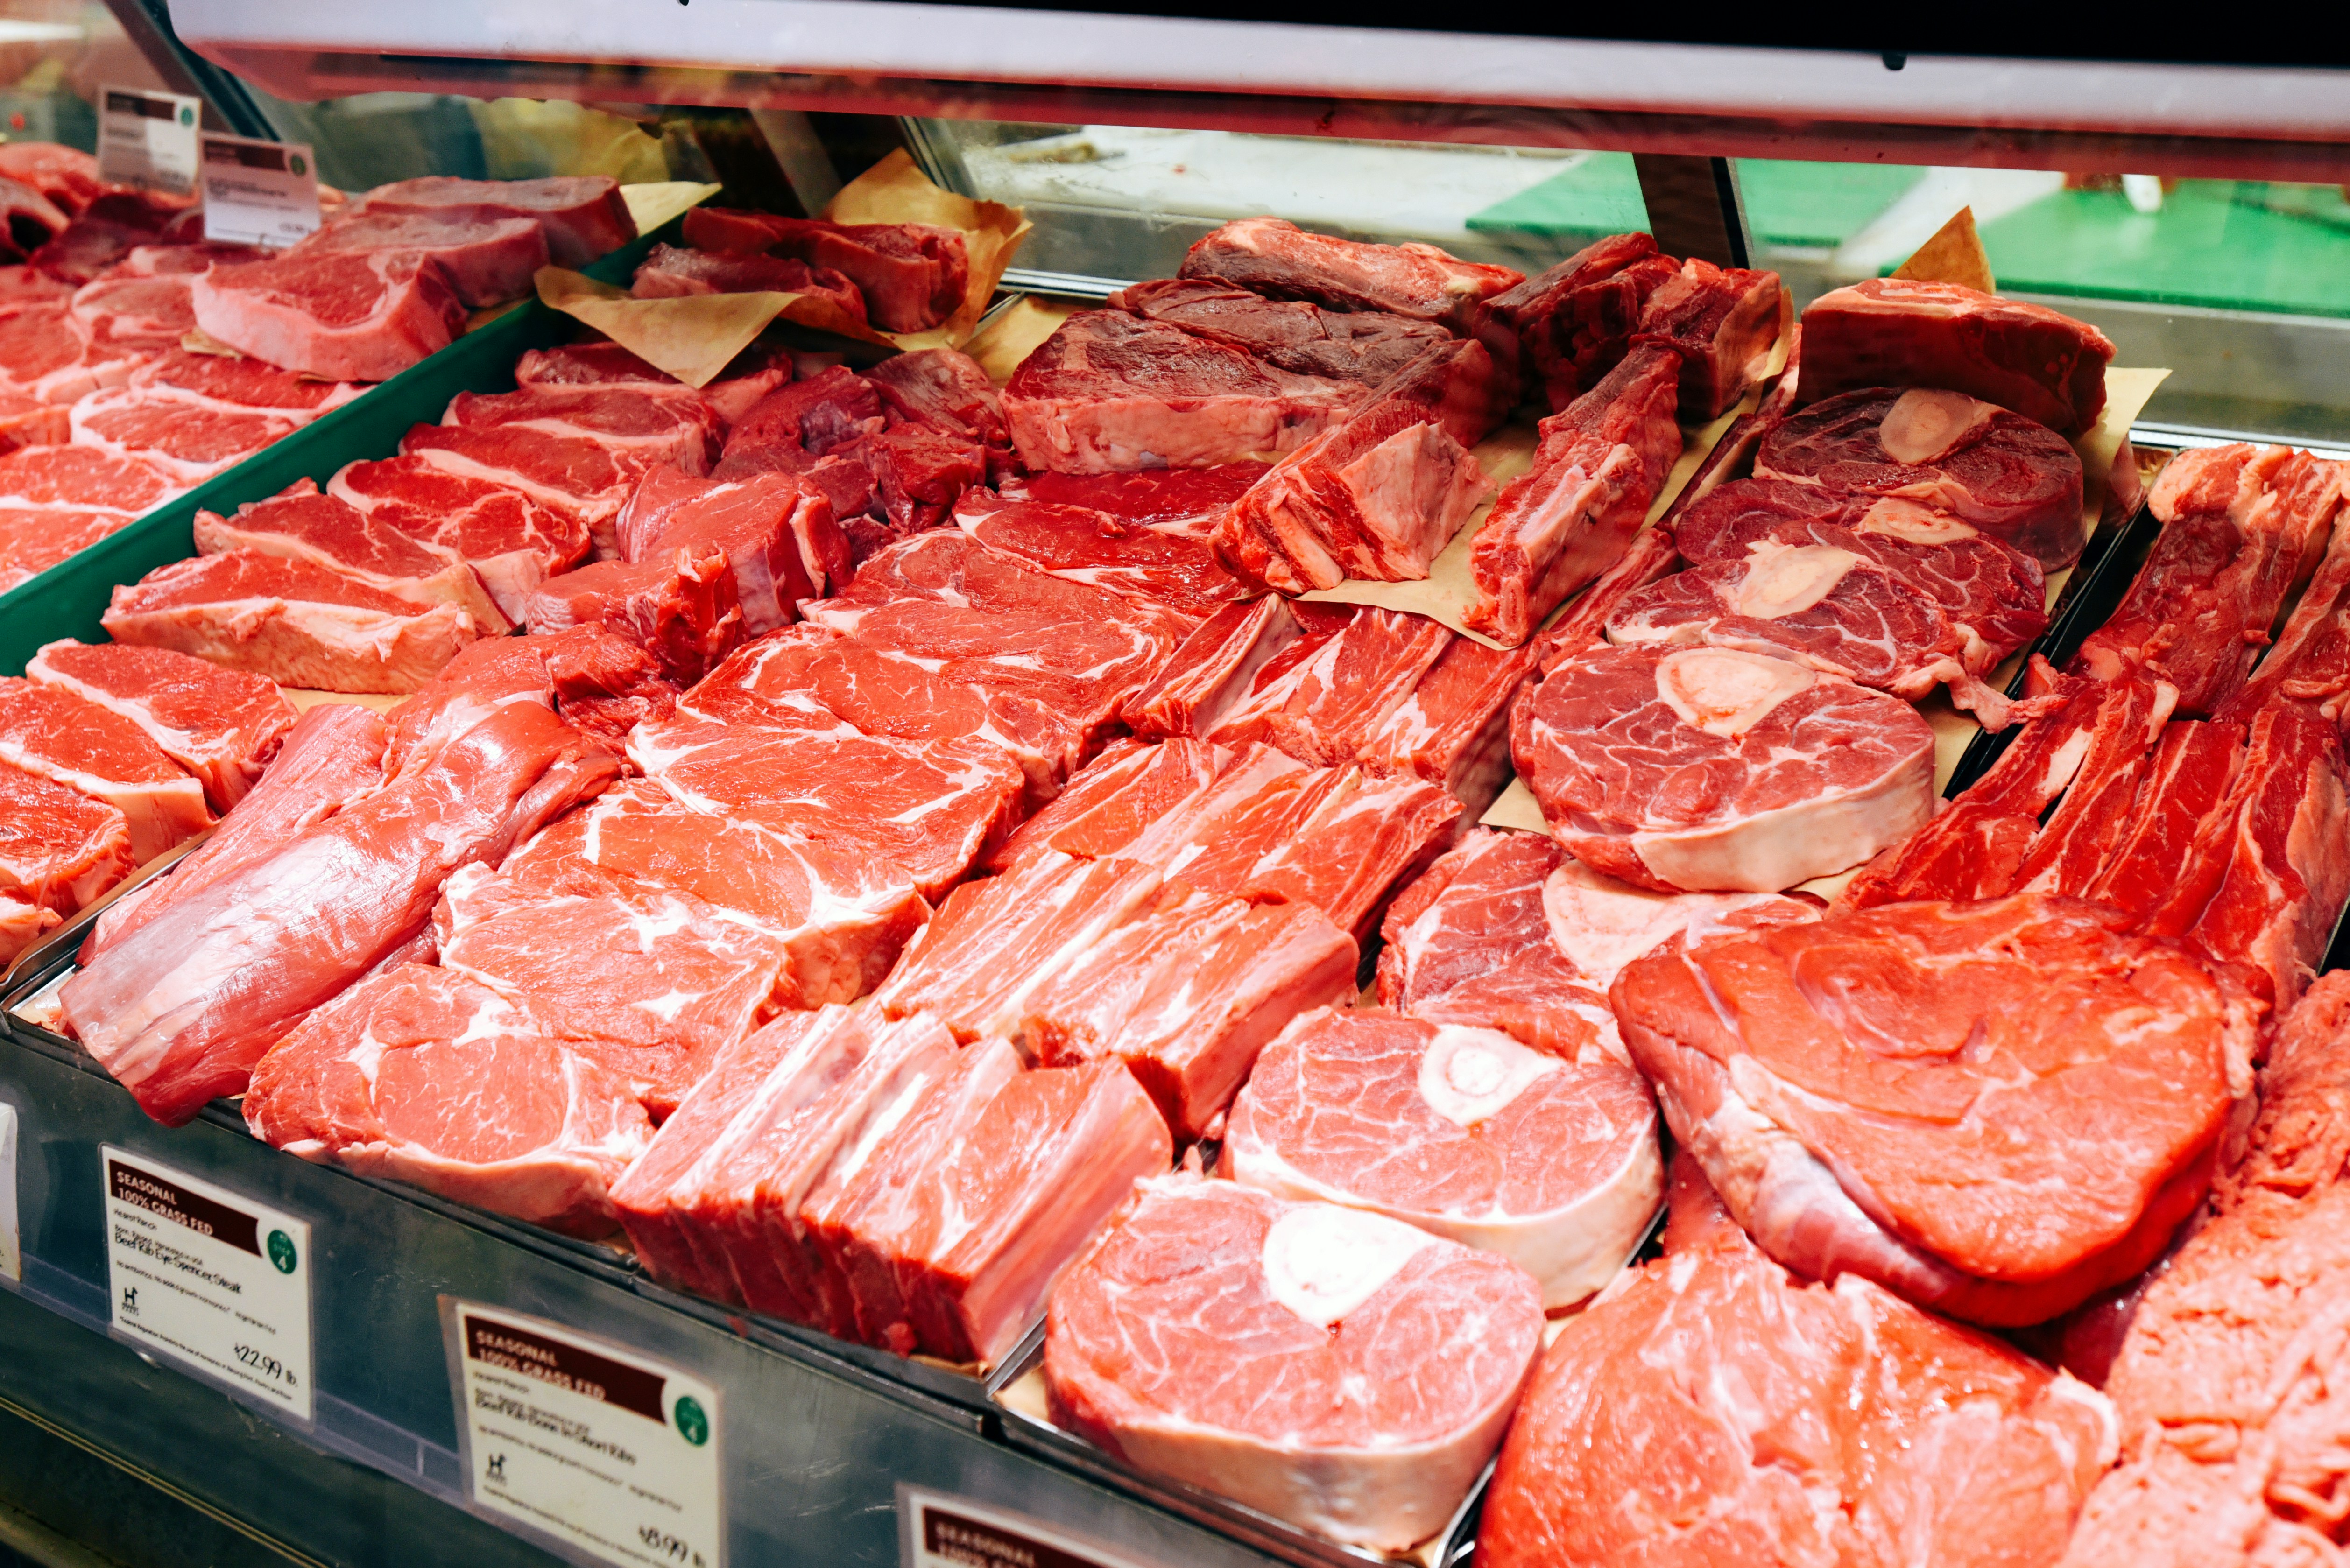
Meat, poultry, fish and eggs accounted for $1,579 of that annual spending. Households spent 11.7% more on those items than in 2024, and twice as much as in 2010. Protein products made up about 24% of grocery spending in 2025, compared with 19% in 2023.

The change in grocery budgets has been concentrated: protein accounted for about 95% of the increase in average food-at-home spending over those two years. That points to a specific pressure within the food category rather than an even rise across every grocery item. The survey figures show the amount households spent, but don’t by themselves distinguish how much came from higher prices, changes in the quantities purchased or shifts in what people chose to buy.
What the figures say about the consumer market
The 2025 results set a useful baseline for businesses watching household demand. Income growth was strong on average, but housing and food occupied more of the spending picture. That split can help explain why consumer sentiment may feel weaker than aggregate income figures suggest: families experience the bills they have to cover before they decide what else to buy.
The source also notes that the survey data came before the Iran war sent some grocery prices and utility costs surging in 2026. Those later pressures are not part of the 2025 spending results, so the reported figures shouldn’t be read as a measure of their full effect. The next useful signals will be updated household spending and income data, along with what businesses see in customer demand as essential costs change.
For operators, the takeaway is to track demand alongside the costs their customers face. The national figures can frame the conversation, but local sales, repeat purchases and customer responses will show how budget pressure is playing out in a particular business.